Speaker: Associate Professor Shen Ji (Guanghua School of Management, Peking University)
Moderator: Assistant Professor Xiong Zeyuan (China Economic Research Institute, Liaoning University)
Guest: Associate Professor He Chao (China Economic Research Institute, Liaoning University)
Time: October 9, 2026 (Friday) 14:30–16:00 (Beijing Time)
Venue: Meeting Room 547, Economics Division Building, Puhe Campus, Liaoning University
Language: Chinese/English
Abstract:
Social interaction is now often part of the consumption of digital products: in online games, fitness apps, and live streams, users interact while they consume, and interaction enhances or dampens a user’s enjoyment depending on whom she encounters. The firm that sells such a product prices something whose value its own users shape. We ask how the firm should price when the price selects not only who participates but whom every participant meets. In a dynamic model with forward-looking consumers, we characterize the stationary equilibrium and compare participation, the elasticity of demand, profit, and the optimal price with a no-interaction benchmark. In the main model, where a consumer’s willingness to pay and her value as a partner are aligned, interaction never lowers the firm’s profit and raises it whenever upward influence exists, even when downward influence dominates; for weak interaction, whether the optimal price falls depends on the distribution of consumer valuations rather than on the direction of influence. In an extension in which willingness to pay and value as a partner are separate characteristics, the price can drive out the very users who make interaction valuable, and interaction can lower profit. We show that whether interaction raises the firm’s profit is decided not only by how positive it is but, more importantly, by whom the price keeps.
Authors Profile:
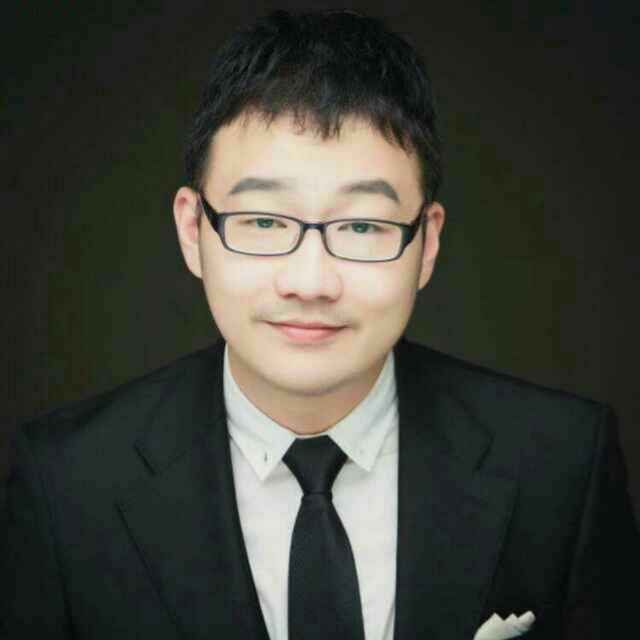
Shen Ji received his Ph.D. in Finance from the London School of Economics and Political Science and is currently a faculty member at the Guanghua School of Management, Peking University. His research interests mainly include asset pricing theory and the digital economy. His papers have been published in both domestic and international academic journals such as Economic Research Journal, The Journal of World Economy, Journal of Financial Research, Review of Financial Studies, Management Science, and Journal of Banking and Finance.